
You walk into a dealership, eyeing that shiny new SUV. The salesperson slides a contract across the desk with a monthly payment that looks surprisingly low. It feels like a win. But then you notice three cryptic lines buried in the fine print: Money Factor, Residual Value, and Cap Cost. If these terms make your eyes glaze over, you are not alone. Most people sign leases without understanding what actually drives their monthly bill.
Here is the reality: leasing is not just renting a car for a few years. It is a complex financial product where small changes in these three variables can swing your total cost by thousands of pounds or dollars. Understanding them turns you from a passive signer into an active negotiator. Let’s break down exactly how these components work together to determine your payment, so you never get caught off guard again.
The Foundation: What Is Capitalized Cost?
Think of the Capitalized Cost (or Cap Cost) as the starting price tag of the vehicle in the lease agreement. This is the most critical number because it represents the amount of the car’s value you are financing. Unlike buying a car outright, where you pay the full sticker price, in a lease, you only pay for the portion of the car you use during the lease term.
The Cap Cost starts with the Manufacturer’s Suggested Retail Price (MSRP), often called the "sticker price." But here is where you have power. You can negotiate this number down, just like when buying. Every pound or dollar you shave off the Cap Cost directly lowers your monthly payment. Conversely, if you roll in extra costs-like extended warranties, service plans, or accessories-those add-ons increase the Cap Cost. A higher Cap Cost means you are borrowing more money, which raises your monthly bill.
There is also something called the "Adjusted Cap Cost." This is the final number used in calculations after subtracting any down payments, trade-in equity, or rebates. For example, if the negotiated Cap Cost is £30,000 and you put down £3,000, your Adjusted Cap Cost becomes £27,000. Always ask the dealer to show you the breakdown of the Cap Cost before signing. If they won’t, walk away. That number is the foundation of your entire deal.
The Hidden Interest Rate: Decoding the Money Factor
If the Cap Cost is the principal loan amount, the Money Factor is the interest rate charged by the leasing company. However, unlike a standard mortgage or auto loan, lease companies don’t quote interest rates as percentages. They use this decimal figure instead, and it is deliberately obscure to keep borrowers from comparing it easily to bank loans.
How do you convert this scary decimal into a familiar percentage? There is a simple formula: multiply the Money Factor by 2,400. So, if a dealer quotes a Money Factor of 0.00150, the calculation is 0.00150 × 2,400 = 3.6%. That is your annual percentage rate (APR). A typical Money Factor might range from 0.00100 (2.4%) to 0.00400 (9.6%), depending on your credit score and the current economic climate.
Why does this matter? Because dealers often mark up the Money Factor. The manufacturer might offer a base rate of 0.00120, but the dealer could present 0.00150 to you, pocketing the difference as profit. This markup is invisible unless you know to look for it. Always ask for the "buy rate" versus the "customer rate." If there is a significant gap, negotiate. Reducing the Money Factor by even 0.00020 can save you hundreds over a three-year lease, especially on expensive vehicles.
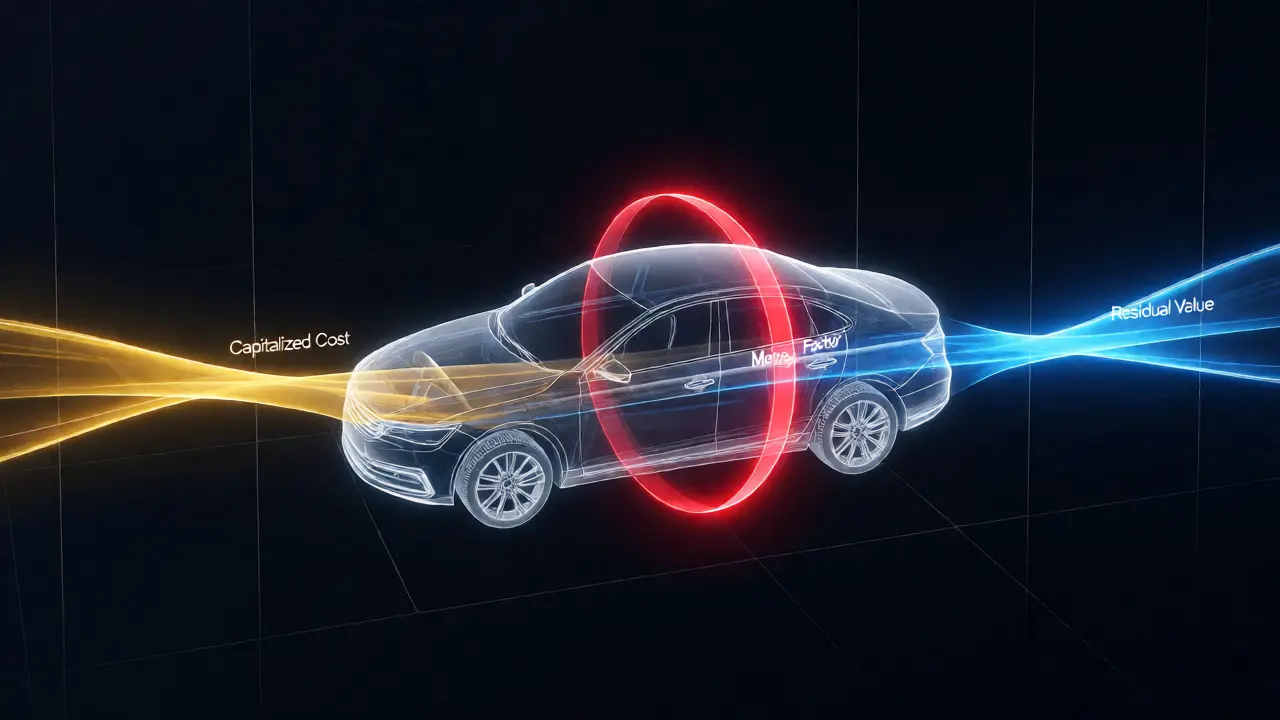
The Crystal Ball: Predicting Residual Value
The Residual Value is the estimated worth of the car at the end of the lease term. It is set by the leasing company before you drive off the lot. Since you are only paying for the depreciation (the difference between the Cap Cost and the Residual Value), a higher residual value means lower monthly payments.
Let’s say you lease a car with a £40,000 Cap Cost. If the residual value is predicted to be £24,000 (60% of MSRP), you are paying for £16,000 of depreciation. If the residual is only £20,000 (50%), you are paying for £20,000 of depreciation. See the pattern? High residual equals low payment. Low residual equals high payment.
| Vehicle MSRP | Residual % | Residual Value | Depreciable Amount |
|---|---|---|---|
| £40,000 | 60% | £24,000 | £16,000 |
| £40,000 | 55% | £22,000 | £18,000 |
| £40,000 | 50% | £20,000 | £20,000 |
Who sets these values? Usually, independent third-party firms like ALG (now part of J.D. Power) analyze historical data to predict future resale prices. Leasing companies rely on these predictions. If a brand holds its value well (like Toyota or Porsche), the residual will be higher, making leases cheaper. If a brand depreciates quickly (like some luxury German cars), residuals drop, raising payments.
Putting It All Together: The Monthly Payment Formula
Now that you know the players, let’s see how they interact. Your monthly payment consists of two main parts: the Depreciation Fee and the Rent Charge (interest).
- Depreciation Fee: (Cap Cost - Residual Value) ÷ Number of Months
- Rent Charge: (Cap Cost + Residual Value) × Money Factor
Notice that the Rent Charge uses the sum of the Cap Cost and Residual Value, not just the difference. This surprises many people. It means that even if you pay off all the depreciation, you still pay interest on the remaining value of the car throughout the lease. This is why high-value cars with long leases can have surprisingly high interest components.
Let’s run a real-world example. Imagine a £35,000 SUV with a £24,500 residual (70%), a £33,000 negotiated Cap Cost, and a 0.00125 Money Factor over 36 months.
- Depreciation: (£33,000 - £24,500) ÷ 36 = £236.11 per month.
- Rent Charge: (£33,000 + £24,500) × 0.00125 = £71.88 per month.
- Total Pre-Tax Payment: £236.11 + £71.88 = £307.99.
If you didn’t understand the Money Factor, you might think the interest is negligible. But here, it accounts for nearly 23% of your pre-tax payment. Negotiating the Money Factor down to 0.00100 would reduce the rent charge to £57.50, saving you roughly £14 a month, or £504 over the lease term.
Negotiation Tactics: Where to Focus Your Energy
Most buyers focus entirely on the monthly payment. This is a mistake. Dealers can manipulate the payment by extending the term, lowering the residual artificially, or hiding fees. Instead, attack the inputs.
Target the Cap Cost first. This is usually the easiest variable to change. Use online pricing tools to find the invoice price (what the dealer paid). Aim to negotiate a Cap Cost close to the invoice, not the MSRP. Even a £1,000 reduction here has a direct impact.
Second, scrutinize the Money Factor. As mentioned, check if the dealer marked up the rate. If you have excellent credit, you should qualify for the best available rate. Don’t accept the first quote. Ask, "What is the buy rate?" If they hesitate, you know there is room to move.
Finally, respect the Residual Value. Unlike Cap Cost and Money Factor, the Residual Value is typically fixed by the leasing company’s program. You cannot negotiate it. However, you can choose vehicles with historically strong residuals. Research brands known for holding value. Avoid models with poor resale track records unless the lease deal is exceptionally aggressive.
Pitfalls and Pro Tips for UK Drivers
If you are leasing in the United Kingdom, remember that VAT (Value Added Tax) complicates things slightly. Most personal leases include VAT in the advertised price, but business leases might treat it differently. Ensure you know whether the quoted Cap Cost and Residual include tax.
Also, watch out for "mileage penalties." While not part of the core financial trio, they interact with residual value. Excess wear and tear can reduce the actual return value below the projected residual, leading to charges at the end of the term. If you drive 15,000 miles a year but sign a 10,000-mile contract, you will pay heavily later.
One last tip: compare the "effective APR." Some dealers advertise low monthly payments by offering cash allowances (rebates) upfront. These rebates lower the Cap Cost but might come with a higher Money Factor. Calculate the true cost of the lease over the full term, not just the monthly sticker.
Can I negotiate the Residual Value?
Generally, no. The Residual Value is set by the leasing company based on third-party forecasts. However, manufacturers sometimes run promotions that temporarily boost residual values on specific models. Keep an eye out for these special offers.
Is a lower Money Factor always better?
Yes, a lower Money Factor means less interest paid. However, ensure that a lower Money Factor isn't offset by a higher Cap Cost. Always look at the total cost of ownership rather than isolated metrics.
What happens if the car's market value drops below the Residual Value?
If you return the car, nothing happens; the leasing company absorbs the loss. If you want to buy the car at the end of the lease, you might find that the market value is lower than the purchase option price (which is based on the Residual Value), making it a bad time to buy.
Does my credit score affect the Money Factor?
Absolutely. Higher credit scores qualify for lower Money Factors. If your score is borderline, improving it before applying for a lease can save you significant interest over the term.
Should I make a large down payment to lower my Cap Cost?
Be careful. In many jurisdictions, including parts of the US, down payments are lost if the car is totaled early in the lease. Gap insurance covers the loan balance, but not necessarily your down payment. Check your local laws and insurance policy carefully.